A buyer’s guide to connecting quotes, customers, invoices, and payment status without compromising the books or customer privacy. This guide is written for a service-business owner seeking to reduce duplicate entry between sales and bookkeeping. It explains the tradeoffs a buyer can check without treating sales claims, product popularity, or advertising promises as independent evidence.
A sound choice starts with the work employees perform on ordinary days, including the exceptions that never appear in a polished sales demonstration. For this subject, the central decision is specific: Keep financial authority in the accounting system while choosing deliberate and reversible CRM synchronization. The examples below are illustrative exercises, not claims that any named supplier has failed or passed an audit. Features, prices, data processing terms, and plan availability can change; verify the actual service before purchasing.
Begin with a decision the organization can defend
Consider the following representative situation: A service-business owner seeking to reduce duplicate entry between sales and bookkeeping. A selection meeting will be more useful if it establishes owners, measurable acceptance criteria, and the information the chosen service must protect. A product demonstration is a starting point for asking better questions; it should not replace a documented trial, a contract review, or a defined recovery route.
Keep financial authority in the accounting system while choosing deliberate and reversible CRM synchronization. Put this sentence at the top of the evaluation worksheet and ask each stakeholder to state which evidence would change their recommendation. That exercise prevents a conversation about attractive features from displacing practical questions about data handling, team adoption, business continuity, and responsibilities after launch.
Eight issues to evaluate in depth
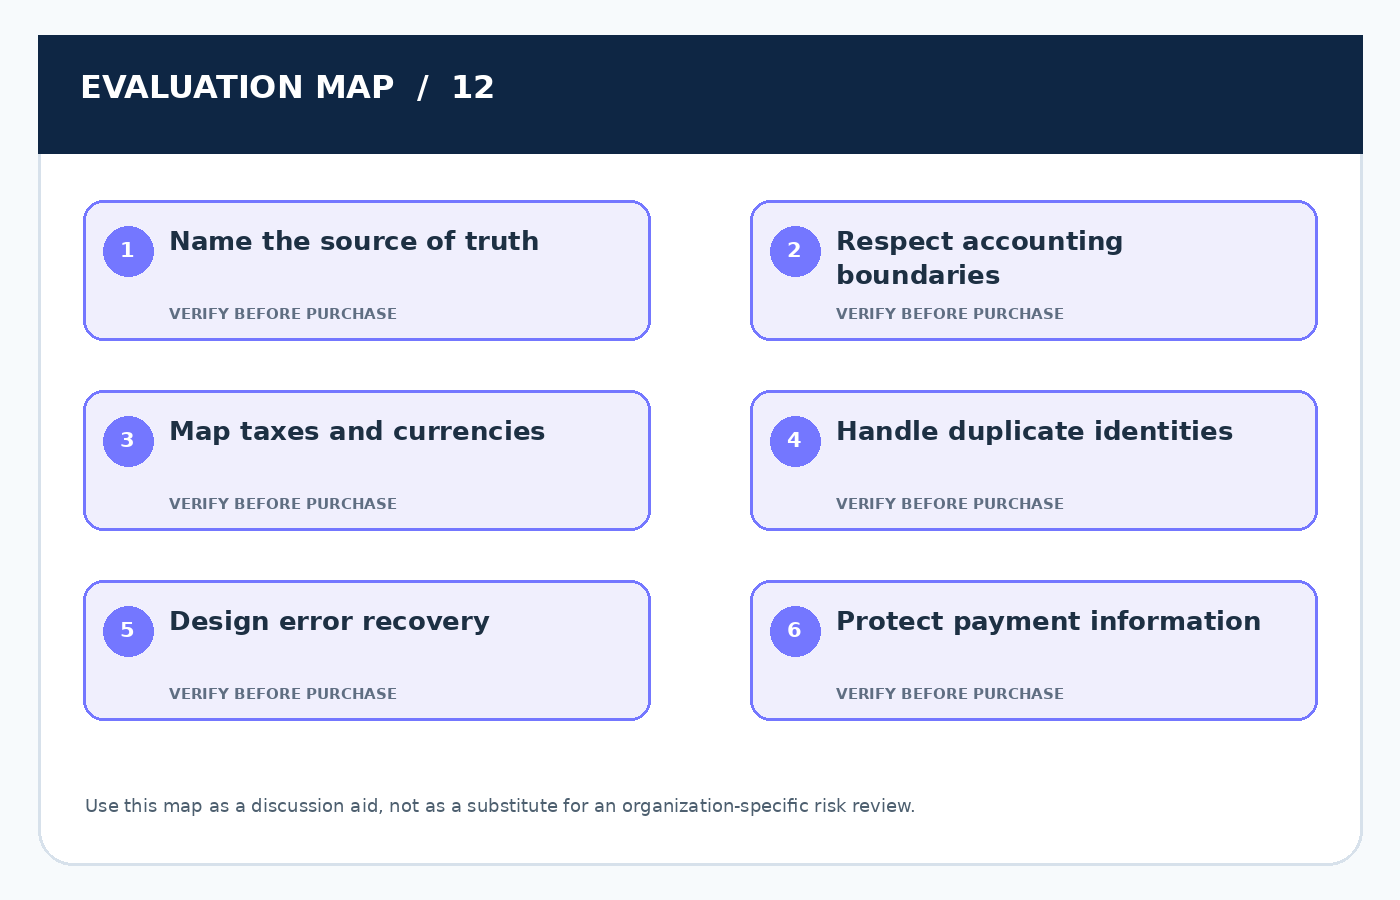
1. Name the source of truth
Decide which tool owns legal entity details, invoice numbers, tax treatment, customer contact preferences, and signed deal status.
Failure to anticipate: Bidirectional sync with no documented precedence can overwrite a verified billing address with an informal sales note from an old lead record.
Evidence to request: Draw a field ownership matrix, identify authoritative updates, and simulate conflicting edits made in both systems on the same day.
2. Respect accounting boundaries
A CRM should not let an unrestricted sales role quietly change journal postings, refunds, or finalized invoices simply because the tools are connected.
Failure to anticipate: Automation built to accelerate quote handoff can accidentally extend invoice adjustment capabilities to employees outside the finance department.
Evidence to request: Review connector scopes, human approval points, role separation, and which actions are permitted after an invoice becomes final.
3. Map taxes and currencies
Products, tax codes, discounts, regional rules, and exchange rates require explicit treatment across quoting and invoicing interfaces.
Failure to anticipate: An opportunity value copied directly into an invoice can become wrong when the CRM uses estimated gross revenue and accounting expects another basis.
Evidence to request: Test several fictional cases including discount, tax exemption, recurring service, credit note, and multicurrency settlement with a finance reviewer.
4. Handle duplicate identities
Sales contacts may refer to multiple people at one organization, while an accounting customer might represent a specific billed legal entity.
Failure to anticipate: Combining records solely by email or company name can attach an invoice to the wrong payer or expose financial status across subsidiaries.
Evidence to request: Define durable identifiers and matching thresholds, queue ambiguous matches for review, and document how merged records will retain historical references.
5. Design error recovery
Payment status, due dates, and invoice updates may fail to sync when tokens expire or an API rejects a field value.
Failure to anticipate: An attractive dashboard can keep showing an outdated paid badge while collections staff continue using different data in the bookkeeping system.
Evidence to request: Create an exception queue, reconcile totals and counts, send useful alerts, and specify who retries or resolves failed transactions.
6. Protect payment information
Many integrations need only payment status or a processor-issued reference, not raw card details or a full transaction credential.
Failure to anticipate: Moving unnecessary payment information into the CRM expands who can view it and what appears in exports, analytics, and support logs.
Evidence to request: Map minimum required fields, confirm the payment provider's supported architecture, and exclude sensitive credentials from customer notes and application logs.
7. Compare operational reports
Sales forecast, contracted revenue, issued invoices, and collected cash are distinct measures and should retain separate definitions.
Failure to anticipate: Executives can make poor decisions if a single dashboard adds open deals to booked invoices or treats uncollected amounts as cash.
Evidence to request: Create metric definitions, include reconciliation examples, and verify that time periods and currencies are aligned across data sources.
8. Plan ownership after launch
Finance, sales operations, and IT need a shared escalation route because data quality and connector failures cross departmental boundaries.
Failure to anticipate: If nobody owns the integration after the consultant leaves, small mapping changes can degrade financial records for months.
Evidence to request: Assign system and process owners, schedule routine reconciliations, review permissions, and test how updates will be promoted from staging to production.
Procurement questions worth writing down
These questions translate the operational discussion into a decision record. Do not send them as an unexplained survey; ask the supplier to demonstrate answers in the actual subscription tier and have the business owner confirm the evidence.
- Name the source of truth: What additional edition, storage, implementation, or integration cost is required to make the promised capability operational?
- Respect accounting boundaries: How would an employee notice that the control failed, and who is accountable for containment and correction?
- Map taxes and currencies: Can the organization retrieve the relevant information and relationships in a usable format if it changes supplier?
- Handle duplicate identities: Which feature depends on another product or subprocessor, and how will material changes be communicated to the customer?
- Design error recovery: What task would staff complete during a vendor outage or a permission-related lockout?
- Protect payment information: Which exact records, identities, or business events are within this requirement, and what is deliberately out of scope?
- Compare operational reports: Can the proposed capability be demonstrated with a fictional but realistic operating example rather than an idealized vendor dataset?
- Plan ownership after launch: Who approves an exception, which evidence is retained, and what event triggers a review or revocation?
A realistic 90-day adoption plan
First 30 days: handle duplicate identities
Document the current workflow, existing software spend, role ownership, and the failure that motivated the purchase. Establish baseline measurements and an information classification before introducing a new subscription or connecting production accounts. The focused activity in this phase concerns handle duplicate identities; use an approved test record and retain the outcome for the rollout decision.
The checkpoint should include the decision owner, a clear pass-or-fail observation, and an agreed route to fix any unresolved issue. A planned launch date alone is not an acceptance criterion.
Days 31–60: compare operational reports
Pilot a representative process with fictional records, compare practical task completion with the incumbent method, and test the main exception paths. Capture the true cost of the required edition, integrations, training, and recurring internal administration. The focused activity in this phase concerns compare operational reports; use an approved test record and retain the outcome for the rollout decision.
The checkpoint should include the decision owner, a clear pass-or-fail observation, and an agreed route to fix any unresolved issue. A planned launch date alone is not an acceptance criterion.
Days 61–90: respect accounting boundaries
Adopt the process gradually, reconcile records and outputs, and assign both an operational owner and an escalation backup. Review costs, access, performance, and recoverability against the written objectives before committing to broader rollout. The focused activity in this phase concerns respect accounting boundaries; use an approved test record and retain the outcome for the rollout decision.
The checkpoint should include the decision owner, a clear pass-or-fail observation, and an agreed route to fix any unresolved issue. A planned launch date alone is not an acceptance criterion.
Frequently asked buyer questions
What should we validate before paying for a solution related to name the source of truth?
Test a small, representative process with fictional records and obtain a written explanation of the service boundaries. The aim is to understand the exact purchased capability, the conditions under which it works, and whether it can be monitored by the customer after launch.
Which hidden risk tends to be overlooked in map taxes and currencies?
The most common evaluation gap is treating the expected operating path as the only possible outcome. Include a negative test, agree on what a failure looks like, and name the individual who will investigate the exception rather than letting a supplier treat it as an edge case.
How can a small team conduct a meaningful trial without a large budget?
Concentrate on one workflow, a limited set of synthetic records, and staff who perform the job. A short, documented trial often produces better evidence than an extensive feature tour with no agreed success criteria. Protect sample information and document what would justify purchasing the next tier.
When should we reconsider the original buying decision?
Reopen the evaluation when the service boundary, pricing, team structure, data sensitivity, or business process changes significantly. Good stewardship is ongoing: the original procurement decision is not permanent authorization for every later use. Reassess unresolved risks and test that transition rights still work.
Official resources and further reading
These sources provide background principles and guidance. They do not endorse the fictional scenarios or certify a vendor mentioned in this article.
- FTC Cybersecurity for Small Business
- NIST CSF 2.0 Small Business Quick-Start Guide
- Microsoft Dataverse: Role-Based Security
Editorial conclusion
The right answer depends on workload, the value and sensitivity of the records, internal capacity, and the precise service terms. For choosing accounting software that integrates safely with your crm, a defensible decision follows from the checks above and from an honest discussion of what cannot yet be demonstrated. Make unresolved questions visible, preserve a practical exit path, and recheck assumptions after the system becomes part of day-to-day work.
Related Posts
Project Management Software for SMBs: A Security-First Buying Guide
How to evaluate task visibility, guest access, document collaboration, automation,…
Cloud File Sharing for Businesses: Comparing Collaboration and Control
A decision framework for document collaboration that includes external sharing,…
Help Desk Software and CRM: Building a Responsible Customer Support Stack
How to connect customer service, contact history, escalation, and reporting…